
…As Emir Sanusi, Others List Benefits Of Non-Interest Finance
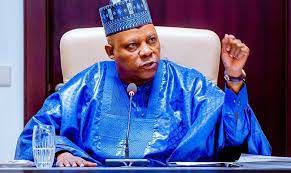
Nigeria’s Vice President, Sen, Kashim Shettima, and other investment experts called on African nations to deepen the adoption of Islamic finance as a tool for inclusive and sustainable economic transformation across the continent.
Shettima made the call while addressing delegates at the 7th African International Conference on Islamic Finance (AICIF), organised by the Metropolitan Law and Metropolitan Skills Ltd in collaboration with the Securities and Exchange Commission of Nigeria (SEC) and held on Tuesday in Lagos.
Represented at the forum by Special Adviser to the President on Economic Matters, Dr. Tope Fasua, at the Conference while speaking on the theme “Africa Emerging: A Prosperous and Inclusive Outlook”, the Vice President said Africa’s demographic advantage must translate into equitable prosperity, stressing that the continent’s progress will be measured not only by growth but by inclusion.
- Advertisement -
He highlighted Nigeria’s recent economic reform initiatives of the President Bola Tinubu’s Renewed Hope Agenda, describing them as key drivers of stability and investor confidence.
According to Shettima, Nigeria has unified its exchange rate, rationalised subsidies, modernised tax and customs systems, and opened new gateways for trade and investment reforms, which have lifted reserves above $40 billion and earned favourable ratings from Fitch and Moody’s.
“These outcomes reaffirm Nigeria’s position as an anchor of the AfCFTA’s $3.4 3.4trn market and a driver of Africa’s growth.”
The Vice President emphasised that Islamic finance provided a credible framework for promoting shared prosperity, rooted in ethics, fairness, and social responsibility, adding that Nigeria’s experience demonstrates the transformative potential of Islamic finance instruments such as Sukuk, Takaful, and Mudarabah,, which have financed critical infrastructure and expanded access to inclusive financial services.
He clarified: “Our Sukuk issuances, now in their seventh cycle, have funded more than 120 major road projects covering nearly 6,000 kilometres. Each bond represents a covenant between government and citizens, proof that finance can build rather than burden.”
Shettima added that Takaful insurance was extending protection to millions of previously excluded households, while waqf endowments are being explored to support schools, hospitals, and small businesses.
Noting that Islamic finance aligns with the government’s conviction that enterprise must serve humanity and wealth must circulate to uplift communities’ the Vice President pointed out that in Africa, countries like Egypt, Senegal, Kenya, and South Africa were developing regulatory frameworks for Islamic banking, Green Sukuk, and socially responsible investments.
The Vice President projected that by 2030, the share of Islamic finance in Africa’s capital markets would significantly grow and urgedpolicymakers to sustain reforms that strengthen transparency, governance, and investor protection.
He also underscored the need to mobilise Africa’s vast domestic capital, including pension funds, sovereign wealth funds, and insurance pools, through innovative instruments such as green sukuk and diaspora bonds.
Shettima said: “Africa’s future must be financed from within, guided by principles of justice, inclusion, and sustainability.”
The Vice President rounded off his remarks by urging participants to “build an Africa where enterprise and empathy coexist, where finance is not a privilege for the few but a promise to the many, and where every child, from Lagos to Lusaka, finds a stake in the continent’s future.”
Earlier, the Conference Chairperson, Ms Ummahani Amin, said that AICIF was conceived as a platform for collaboration and knowledge sharing to advance Islamic finance as a viable alternative source of funding for Africa’s socio-economic needs.
The investment expert noted that while Islamic finance assets globally reached $3.88 trillion in 2024, Africa still lags behind in harnessing its full potential to close the continent’s annual infrastructure financing gap of up to $170 billion.
She emphasised that challenges such as limited liquidity, weak market infrastructure, and inadequate investor education must be addressed for Islamic finance to reach its potential.
Amin said: “Artificial intelligence is also reshaping finance across the continent, from automating compliance to personalising ethical investment, and we must ensure ethical guardrails guide its use.”
In his opening remarks, SEC Chairman, Mr. Mairiga Katuka, said Nigeria’s non-interest capital market had grown rapidly under the Capital Market Masterplan (2015–2025), with sovereign Sukuk raising over N1.4 trillion and funding 124 critical road projects nationwide.
Katuka noted that Nigeria now has 19 registered halal mutual funds managing over N112 billion in assets, up from one fund in 2008, and pledged the SEC’s commitment to evolving regulatory frameworks for innovations such as innovative sukuk, tokenisation, and blockchain-enabled transparency.
The two-day conference also featured a startup pitch competition supporting innovations in technology and social impact, as well as an awards ceremony honouring individuals and institutions contributing to the growth of Islamic finance across Africa.
In his remarks, Emir of Kano, Alhaji Sanusi Lamido Sanusi, urged Islamic finance institutions across Africa to focus more on supporting small and medium enterprises (SMEs) in underserved communities as a pathway to achieving shared prosperity and sustainable development.
Sanusi, a former Governor of the Central Bank of Nigeria (CBN), emphasized that Islamic finance can only make a meaningful impact when it directly addresses the financial exclusion faced by small businesses and vulnerable groups.
The traditional ruler said: “I would be happier to see Islamic banks that are big, but more importantly, ambitious enough to grow a market that delivers real value to people and helps reduce poverty. We need to begin now to see how we can use finance to create opportunities for the small people.”
The Emir underscored the need for Islamic financial institutions to go beyond conventional models by extending services to the grassroots, where the majority of Africa’s unbanked population resides, while also calling for bold strategies that bridge cultural and social barriers, which have historically hindered access to finance, particularly for women.
He said: “Go to the grassroots, have the courage to build and connect with the cultural conceptions and attitudes that have denied women. The empowerment of women is what will contribute to prosperity in Africa.”
Sanusi reiterated that inclusive finance remains central to Africa’s economic transformation, urging Islamic finance stakeholders to leverage their principles of equity, risk-sharing, and social responsibility to foster a more just and prosperous continent.
The conference, co-hosted by the Securities and Exchange Commission (SEC), brought together regulators, scholars, development partners, and investors from across the African continent.